

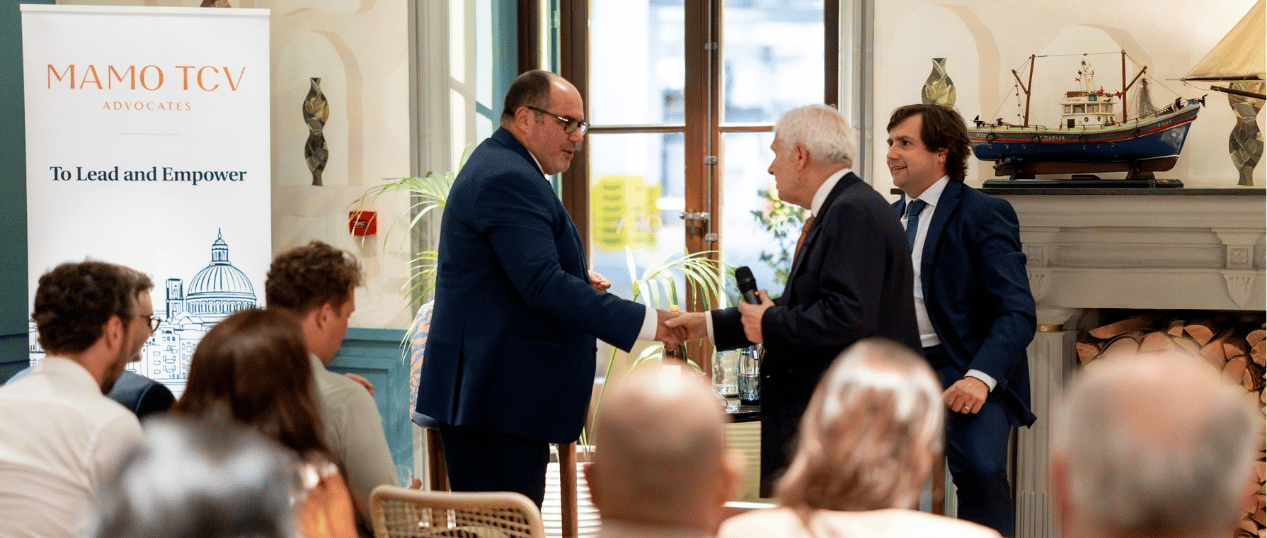
Mamo TCV Advocates recently partnered with the Malta Business Network to host Runway Finance: Lease Finance in Aviation, an event bringing together aviation professionals, financiers and legal practitioners to discuss the recent developments reshaping aircraft financial leasing and what they mean for Malta’s aviation finance sector. Malta is introducing new legislation that would provide qualifying lessors with a streamlined, notification-based alternative to a full financial services licensing, so the discussion came at a timely moment for the industry. Aeroitalia was represented by Marco Carcioffo, VP Fleet & Purchasing, who has over 18 years of experience across fleet management, operations and consulting, including roles at Blue Panorama Airlines and Air Italy. The discussion and the Q&A session that followed were moderated by Dr. Nicholas Valenzia, Partner at Mamo TCV Advocates and head of the firm’s Shipping and Aviation Departments. Nicholas has extensive experience in aircraft ownership, operational and finance structures, and in repossession procedures on behalf of various international credit institutions.
We now proceed to consider some of the salient aspects of the topics touched upon during the conversation.
Types of Aircraft Leases
Aircraft leasing constitutes a significant part of aviation finance, allowing airlines to operate an aircraft without purchasing it outright.
Given the high cost of acquiring and operating aircraft, leasing can provide airlines with greater financial and operational flexibility. There are several types of aircraft leases, which can broadly be distinguished according to their financial structure and the operational responsibilities of the parties. A distinction is made between wet and dry leases, which focuses primarily on who is responsible for operating the aircraft and providing the necessary crew and services. Arrangements may also exist which fall somewhere between a traditional wet lease and a dry lease, such as a damp lease, where only certain operational services are provided by the lessor.
The nomenclature used by the parties is not conclusive. The classification of a leasing arrangement depends on its substantive terms and the allocation of rights, obligations and operational responsibilities between the parties, rather than solely on the description given to the lease. .
Wet Leases
A wet lease is an arrangement under which the lessor provides the aircraft together with operational services, commonly referred to as ACMI: aircraft, crew, maintenance and insurance. The aircraft is generally operated under the lessor’s Air Operator Certificate (AOC), meaning the lessor retains operational responsibility for the aircraft.
Wet leases are commonly used where an airline needs additional capacity at short notice, for example during periods of increased demand, while an aircraft is undergoing maintenance, or where it does not have sufficient aircraft or crew of its own. Depending on the terms of the agreement, the lessee will generally remain responsible for costs such as fuel and airport charges. Wet leases are often used for short-term arrangements, although the length of the lease can vary depending on the needs of the airline.
Dry Leases
A dry lease, in contrast, involves the lease of the aircraft without crew or operational services. The lessee is responsible for providing the flight and cabin crew and for arranging the aircraft’s maintenance, insurance and other operational requirements. The aircraft is operated under the lessee’s AOC, therefore, the lessee assumes operational responsibility and integrates the aircraft into its own fleet.
Dry leases can be used for both short and long periods and are particularly suitable for airlines that have the necessary operational infrastructure and regulatory approvals to operate the aircraft themselves. Moreover, dry leases may occur in two different forms: Operational leases or Financial Leases.
Operating Leases
An operating lease is an arrangement under which the lessor retains legal title to and the economic interest in the aircraft throughout the lease term, while the lessee pays periodic rent for the right to use the aircraft. Unlike a finance lease, an operating lease is primarily intended to provide the lessee with the use of the aircraft for a specified period rather than to facilitate the acquisition of the aircraft. At the expiry of the lease term, the aircraft is generally returned to the lessor.
Finance Leases
A finance lease is a long-term leasing arrangement under which the lessor acquires or owns an aircraft and leases it to the lessee in return for periodic payments over an agreed term. In contrast to an operating lease, the lessee assumes substantially all of the risks and rewards associated with ownership of the aircraft, although legal title generally remains with the lessor during the lease term. The lease payments are structured to enable the lessor to recover its investment in the aircraft, together with an appropriate return on that investment. Depending on the terms of the agreement, the lessee may also be granted an option to purchase the aircraft at the end of the lease term.
The distinction between an operating lease and a finance lease is not always clear cut and may depend on the specific terms and structure of the relevant leasing arrangement. In practice, the two forms of lease may share several characteristics, and the legal and economic substance of the particular transaction should therefore be considered carefully when determining its nature and the rights and obligations of the parties.
While finance leases are often used as a means of financing the acquisition or use of an aircraft, they should be distinguished from debt financing, as the legal structure and ownership arrangements differ significantly.
Debt Financing
Under debt financing, a company borrows funds to acquire an aircraft, with legal title and ownership vesting directly in the company upon acquisition. The aircraft forms part of the company’s assets from the outset, while the company remains liable to repay the borrowed funds, together with any applicable interest, in accordance with the financing agreement.
New Legislation on Aircraft Financial Leasing
The discussion also focused on the introduction of the new regulatory framework. The Malta Financial Services Authority (“MFSA“) intends to introduce a light-touch, notification-based regime built around a List of Aircraft Financial Leasing Companies, which the MFSA would maintain under the Financial Services Register. Lessors incorporated in Malta with at least EUR 100 million in aggregate assets could notify the MFSA to be included on the List, allowing them to carry out aircraft and engine financial leasing without a financial services license. To qualify, they would need to meet a defined set of conditions, including a Maltese resident director, an activity restriction limited to aircraft and engine leasing, and the appointment of an approved Due Diligence Service Provider. Once admitted, they would be subject to ongoing governance, AML/CFT and reporting obligations. The MFSA first consulted on the framework in January 2026. In July 2026, this was followed with a second consultation on the draft Rules for Notified Aircraft Financial Leasing Companies and Related Due Diligence Service Providers, for which comments closed on 31 August 2026. The proposed regime offers qualifying lessors an efficient route to the local market while keeping the oversight that international counterparties expect and marks a further step in establishing Malta as a leading jurisdiction for aviation finance.
This document does not purport to give legal, financial or tax advice. Should you require further information or legal assistance, please do not hesitate to contact info@mamotcv.com